
[DRAFT] Navigating 1.5°C Overshoot: Priorities for The Next Era of Climate Finance
By: Ronan Hodge
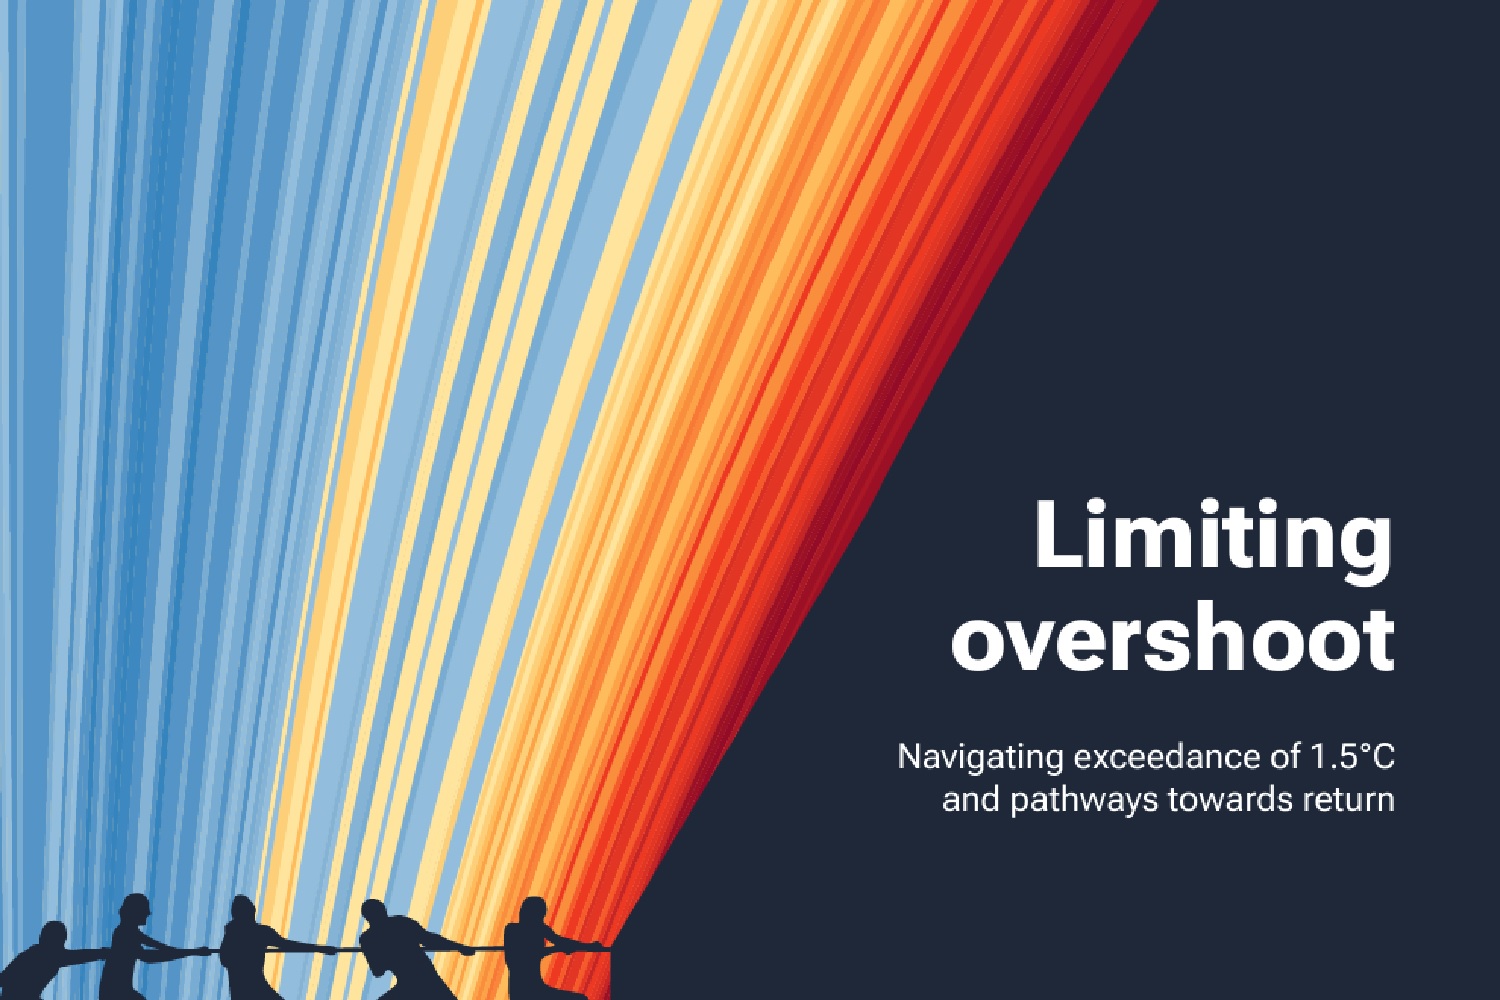
A key talking point in recent weeks has been the recent UNEP report ‘Limiting Overshoot’ that notes exceedance of 1.5°C is now widely assessed as unavoidable and examines the implications of entering an era of 1.5°C overshoot .
The ambition to limit warming to 1.5°C was a key element of the Paris Agreement and viewed as existential for the low-lying countries that fought for inclusion of the target in negotiations.
But limiting temperature rise to 1.5C has seemed increasingly unlikely with emissions still edging higher and temperatures already nudging 1.5C – the building El Nino is expected to see them shatter records at around 1.7C next year.
Amid the potential for despair, the UNEP report seeks to maintain focus on 1.5C as the ultimate target while recognising it will be exceeded (‘overshoot’) by exploring the pathways needed to enable temperature decline in future.
Three implications for climate finance stand out, and have become increasing talking points through event agendas and on the sidelines at climate convenings in recent weeks.
First, Adaptation & Resilience becomes more important as higher medium term temperatures are baked in, even in best case scenarios.
Adaptation was not so long ago a taboo in climate circles: ‘thinking we can just adapt will distract from mitigation’. But increasing frequency and severity of extreme weather events – successive heatwaves across Europe, and the devastating Nepalese glacier collapse among the most recent examples – have already raised adaptation up the agenda. A recent survey found 94% of major companies globally have experienced financial loss from climate-related supply chain disruption in the past two years.
A common misconception, is that adaptation is purely a cost and so investments are only for the public sector. Earlier this year GFANZ pulled together 22 case studies that reveal how financial institutions are financing a range of adaptation and resilience solutions across advanced and emerging economies, often with no public funding involvement at all. As building resilience to climate risks grows in importance, it will be key to continue drawing on innovative financial approaches and scaling what works, through effective public-private collaboration, clear policy direction, and targeted public investment.
Second, carbon removals have an ever more critical role if we are to bring temperatures down.
This too crosses an old taboo that removing carbon is merely ‘spitting in the wind’ while emissions remain high and can distract from action on decarbonisation. To support carbon removals at scale, whether through nature or technological solutions, will require economic incentives to capture and store carbon. This is where high-integrity carbon markets will be essential, particularly project-based credit markets that many jurisdictions are now integrating as a way to meet formal emissions obligations. As efforts to build integrity in these markets get traction, policymaker attention is focused on how to support demand. Earlier this year the Coalition to Grow Carbon Markets, made up of 14 countries, announced it would produce a Policy Playbook that is slated for release at COP31 to support countries and showcase successful approaches.
Finally, the near-term warming impact of methane emissions makes cutting them critical to mitigate the scale of overshoot.
Methane breaks down naturally in around 12 years but over a 20 year period, it traps roughly 80 times more heat than carbon dioxide. But the standard approach to collectively considering greenhouse gases considers warming over a 100 year period which has the effect of massively understating methane’s near-term warming impact. To limit the size of any temperature overshoot, tackling methane is key and there is increasing clamour for pulling out methane targets as distinct from carbon emissions. Key sectors for methane are agriculture and oil & gas production, so here too we’ve encountered a taboo - ‘climate finance shouldn’t be going to fossil fuel companies, even to reduce the emissions of their activity’. But the role of finance is increasingly being recognised whether through engagement with the O&G sector on its methane emissions on areas such as leaks and flaring - work by the IEA and ETC show the bulk of methane emissions abatement comes at no cost given the non-emitted methane can be sold - notably the market price has [doubled] this year. The Methane Finance Working Group has published guidance that can help the oil and gas industry move from the climate commitments they have made to implementation while also enabling companies to gain a competitive edge as world markets increasingly demand lower emissions gas.
Climate finance is moving past old taboos and developing solutions that can enable the investment in adaptation, carbon removals, and methane abatement that are increasingly recognised as essential if we are to meet the realities of overshoot and secure long-term climate stability.
About the Author
Ronan Hodge is the Technical Lead at the Glasgow Financial Alliance for Net Zero (GFANZ), overseeing workstreams supporting the implementation of net-zero transition planning by financial institutions and their clients.